Separate ILOE job-loss insurance from WPS, private cover and health insurance. Check benefits, eligibility, claims timing and the gap in your household budget.
“Salary protection” can mean several different things in the UAE. The Wage Protection System concerns salary payment; ILOE provides a defined unemployment-insurance benefit; a private policy may cover a different event or pay a lender rather than replace your household income. Check which problem you are trying to solve before comparing premiums.
If you have already lost your job, start with the current claim instructions and deadline for a policy you already hold. A newly bought policy should not be assumed to cover an event that has already happened. If you are planning ahead, read the actual wording, not a general promise of financial peace of mind.
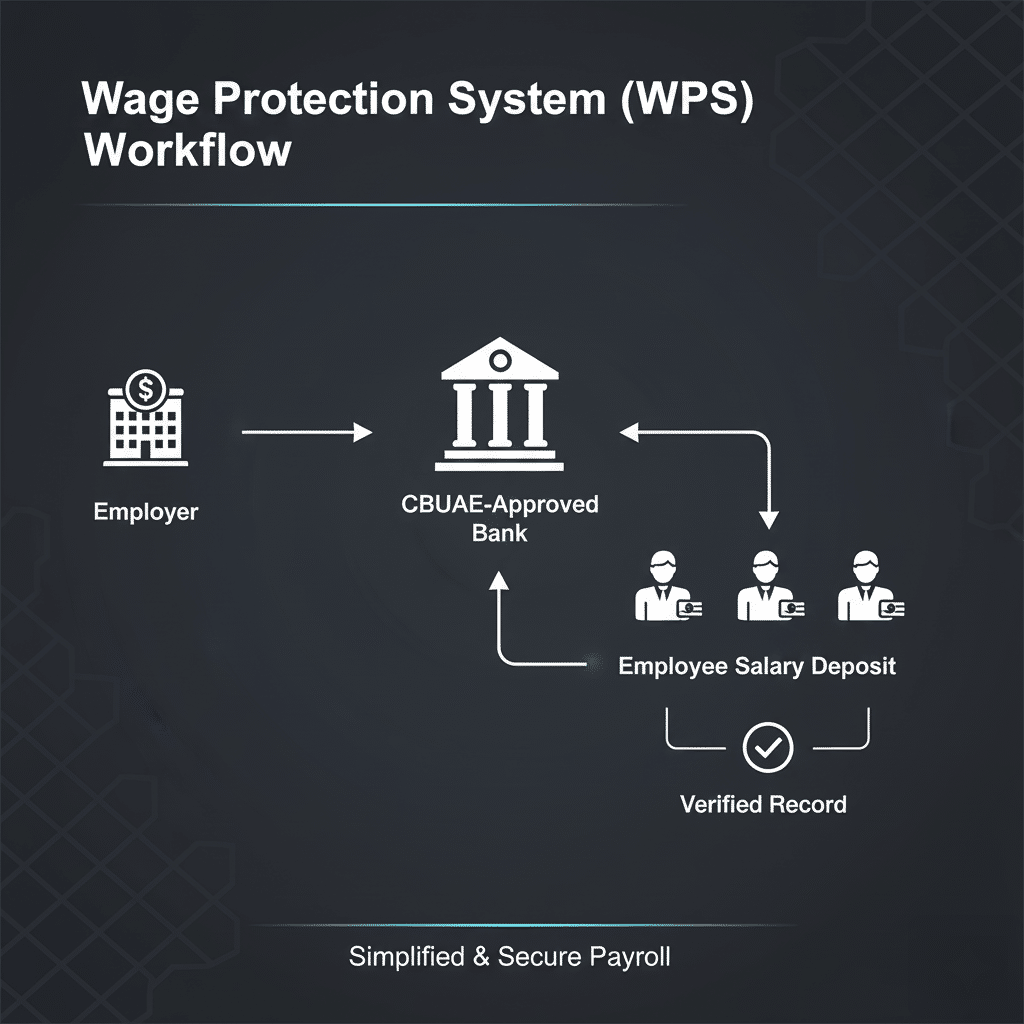
Four protections, four different questions
| Protection | Question it addresses | What not to assume |
|---|---|---|
| Wage Protection System (WPS) | How an employer pays wages through the applicable system | It is a policy paying future income after job loss |
| ILOE | Whether an insured involuntary job loss meets the scheme’s benefit conditions | It replaces every dirham of your total salary indefinitely |
| Private insurance | What event the specific contract covers and to whom it pays | Every product called income protection includes redundancy |
| Health/illness/disability cover | The specific treatment, diagnosis or incapacity insured by the policy | It necessarily pays an unemployment benefit when you are fit to work |
For overdue wages rather than job-loss insurance, use the relevant employment complaint route. Our salary-payment guide is a different topic from claiming an unemployment policy.
ILOE: the published starting point
The official ILOE scheme page, checked on 18 October 2026, calculates eligible monthly compensation at 60% of the average basic salary over the six months before involuntary job loss. Basic salary is not automatically the same as salary including housing and other allowances.
| Published category | Basic salary band | Published premium | Maximum monthly benefit |
|---|---|---|---|
| A | AED 16,000 or below | AED 5 plus VAT per month | AED 10,000 |
| B | Above AED 16,000 | AED 10 plus VAT per month | AED 20,000 |
The scheme lists up to three months per claim and an aggregate limit of 12 monthly benefits over the insured person’s UAE working life. Category caps are ceilings, not amounts every subscriber automatically receives. Check the current policy period, billed total and payment conditions when subscribing or renewing.
The claim conditions matter as much as the benefit
The official ILOE FAQ, checked again on 28 October 2026, requires at least 12 consecutive months of subscription and excludes resignation and disciplinary dismissal. Its general claim instruction says within 30 days of termination. Its eligibility section also refers to 30 days from settlement of a labour complaint referred to court. If that qualification affects you, contact ILOE promptly to confirm the applicable deadline; do not assume any complaint pauses it. Full eligibility and cessation conditions still apply.
Do not confuse the required insured period before eligibility with a private policy’s waiting time after a loss. They are different clocks. Use the actual termination date, subscription record and official claim instructions instead of a generic “wait 60 days” example. If circumstances are disputed, obtain guidance from the scheme and the appropriate employment authority.
Keep the policy record, payment evidence and employment documents accessible. If a premium or status record is wrong, contact the scheme rather than assume a screenshot of an old subscription resolves it. This article does not determine an individual claim or replace the insurer’s current document requirements.
A basic-salary example exposes the household gap
Consider an illustrative employee with AED 20,000 total monthly salary, consisting of AED 12,000 basic pay and AED 8,000 allowances. Assume the average basic salary for the relevant six months remains AED 12,000 and the claim meets every condition.
| Illustrative monthly amount | Calculation | Result |
|---|---|---|
| ILOE benefit before other case-specific adjustments | 60% × AED 12,000 | AED 7,200 |
| Benefit as a share of total salary | 7,200 ÷ 20,000 | 36% |
| Essentials budget | Assumed actual expenses | AED 10,000 |
| Gap against that budget | 10,000 − 7,200 | AED 2,800 |
Three months of that monthly gap would total AED 8,400. After a maximum three-month claim ends, do not continue counting the benefit as though it were permanent income. The example does not establish this employee’s eligibility, payment date, tax treatment elsewhere or an available private-insurance quote.
Make the budget useful by listing actual rent, food, utilities, transport, school fees, debt payments and any costs affected by the job ending. Include when bills fall due, not only a monthly average. An annual school payment or rent cheque due next week can create a cash problem even if a spreadsheet’s annual total looks manageable.
Accessible savings and insurance answer different timing problems
A policy may require documents and an accepted claim before money is available. Keep the cash needed for near-term commitments separate from a potential benefit. The right accessible reserve depends on your bills, dependants, other income and risks; no single three-to-six-month figure is a universal guarantee of adequacy.
Do not count the same money twice. A possible gratuity, unpaid salary, an insurance claim and a deposit refund are separate receivables with different conditions and timing. Use amounts you can substantiate and label uncertain receipts as uncertain. Our job-change guide helps separate employment steps from residence and permit questions.
Private salary or income cover: ask what the contract actually insures
Do not compare an advertised premium with an assumed payout. For any quote, obtain the insurer, product name, policy wording, benefit schedule and eligibility assessment. A useful comparison must identify the covered event, benefit limits and who receives the money.
A named example shows why the payment recipient matters. ADCB’s Credit Shield page describes job-loss cover calculated from credit-card debt rather than salary. The main policy linked from that page names ADCB as the policyholder and makes it the beneficiary for covered outstanding-debt benefits, including involuntary job loss. That is different from assuming an unrestricted salary replacement for rent and groceries. The linked wording has card-category exclusions and claim conditions; obtain the wording and amendments applying to your own cover rather than assume this document determines your eligibility. For a household budget, do not add a debt-cover maximum to the ILOE benefit as spendable cash without checking the actual settlement and any benefit interactions.
| Question | Why it matters |
|---|---|
| Is the insured event involuntary unemployment, illness, disability or death? | Those are different triggers; a reassuring product name does not define coverage |
| Who receives the money? | A bank’s credit-protection payment may service a debt rather than become household cash |
| Is the salary basis basic, gross or another defined amount? | A percentage without its base cannot be compared |
| What are the initial exclusion and post-loss waiting periods? | One affects when cover becomes usable; another affects when benefits may begin |
| Is there a monthly cap and maximum benefit period? | A high advertised percentage may be constrained by both |
| How does it interact with ILOE or another policy? | Do not add benefits together unless the contract permits it |
| What changes end cover or must be reported? | A new role, residence change or other event can affect the actual policy |
The answers should refer to clauses, not a salesperson’s assurance that a claim will “definitely” pay. Ask about probation, contract type, known redundancy, voluntary departure, misconduct, employer closure and documentation. Conditions vary; this guide does not establish that every insurer uses the same exclusions, ages, employment duration or benefit percentages.
Never conceal a known circumstance when applying. If a question is unclear, ask for written clarification and provide accurate information. Whether a specific situation is covered must be assessed against the actual disclosure and contract, not an article’s categorical yes or no.
Check the insurer and intermediary separately
The Central Bank’s licensing information is a starting point for checking the relevant onshore insurer and insurance activity. Establish the full legal insurer and who is selling or advising on the product. A broker, comparison website and insurer are not interchangeable, and a logo alone is not a licence check.
For an unresolved complaint, follow the provider’s formal process and obtain the applicable escalation route. The Central Bank contact page directs complaints about licensed financial institutions and insurers to Sanadak. Check admissibility and process for your case rather than assume an outcome or deadline from a general guide.
A comparison sheet to take to the provider
- Exact insured event and policy clause.
- Insurer, intermediary and licensing details.
- Eligibility and the facts on which the quote depends.
- Full premium and billing commitment, including taxes and fees.
- Salary definition, benefit formula, cap, duration and payment recipient.
- Initial exclusion period, any waiting period and claim-notification deadline.
- Documents, exclusions, benefit interactions and when cover ends.
- Cancellation/refund terms and the complaint route.
Choose only after the policy solves a gap you have actually identified. A cheaper premium can mean less relevant cover, while a larger maximum benefit can still be unavailable to your situation. Compare matched risks and conditions rather than announce one “best” policy without evidence.
Two details to check before submitting an ILOE claim
ILOE’s linked Claims Submission Guideline gives separate routes for private-sector, federal-government and non-MOHRE employees. Use the section matching your employment status rather than treating one document checklist as universal.
In the private-sector walkthrough, the scheme tells applicants to add remarks and supporting documents if the displayed cancellation date or reason is wrong—not confirm an incorrect entry. For bank-transfer payment it also warns that the system does not verify your IBAN, so check it against your own bank record before submission. If records or the deadline are unclear, the official FAQ lists 600 599 555 as a claim channel. These are published instructions, not a claim we submitted or a promise of acceptance.
If the job has already ended
Record the termination date, retrieve the policy and promptly check official claim requirements. Keep correspondence and submit accurate documents through the actual insurer or scheme channel. Separately deal with salary or gratuity disputes, permit/residency status, health cover and immediate household bills; an insurance claim does not settle all of those matters.
This guide explains published scheme information and questions to ask; it is not personalised financial, insurance or legal advice. Obtain appropriately licensed advice for an assessment of a specific product or situation.
Questions answered
Is WPS the same as ILOE?
No. WPS concerns wage payment; ILOE is unemployment insurance with its own eligibility, benefit and claim conditions.
Is ILOE calculated from my full salary package?
The published formula uses the average basic salary for the six months before involuntary job loss, subject to category caps and full eligibility conditions.
What should I check first after termination?
Check the claim deadline and requirements for your existing policy promptly. ILOE’s FAQ says within 30 days of termination and separately qualifies this by reference to settlement of a labour complaint referred to court. Confirm the applicable deadline with ILOE; do not assume every complaint pauses it.
Can I assume a private policy adds to ILOE?
No. Read the actual policy’s benefit interactions, insured event, payment recipient and limitations before adding potential payouts together.