I would reject any crypto-staking pitch that explains the yield but cannot explain how you get your money out. Rewards are only one part of the decision. The asset can fall in value, a provider can restrict withdrawals and the product called “staking” may be doing something quite different from supporting a blockchain.
Crypto staking in the UAE is not a savings account or a guaranteed AED income stream. Start with the mechanism, the contracting entity’s actual permissions and the exit terms. This guide explains those distinctions, the relevant UAE regulatory and tax questions, and a worked example of why a positive token yield can still produce a substantial dirham loss.
What staking actually means
In proof-of-stake networks, validators commit assets and perform network duties under the protocol’s rules. Rewards depend on those rules and participation. A person can run infrastructure, delegate where the network supports it, use a pool or buy a provider’s service. Those routes involve different control and risk arrangements; simply holding an asset in an ordinary wallet does not automatically earn staking rewards.
Bitcoin itself uses proof-of-work, not native proof-of-stake. A product advertising a BTC yield needs its own explanation: lending, wrapping or another external arrangement is not Bitcoin consensus staking. The Bitcoin symbols in this article’s illustration do not establish that mechanism.
| Arrangement | What to establish | Main additional question |
|---|---|---|
| Direct validator operation | The protocol deposit, infrastructure, keys and operating duties. | Can you operate it correctly and manage the penalties and exit process? |
| Native delegation | What rights are delegated and who retains spending control. | What does this network do when a validator underperforms? |
| Pooled or liquid staking | The operators, contracts, fees and any receipt token. | How do redemption and secondary-market sale differ? |
| Custodial staking or exchange Earn | The exact legal product and provider terms. | Is the return from validators, lending, trading or something else? |
The benefits can include network participation and token rewards without actively trading. They do not cancel capital risk. I would not use a bank-interest analogy without making that difference explicit: the asset, withdrawal rights and loss protections are not the same.
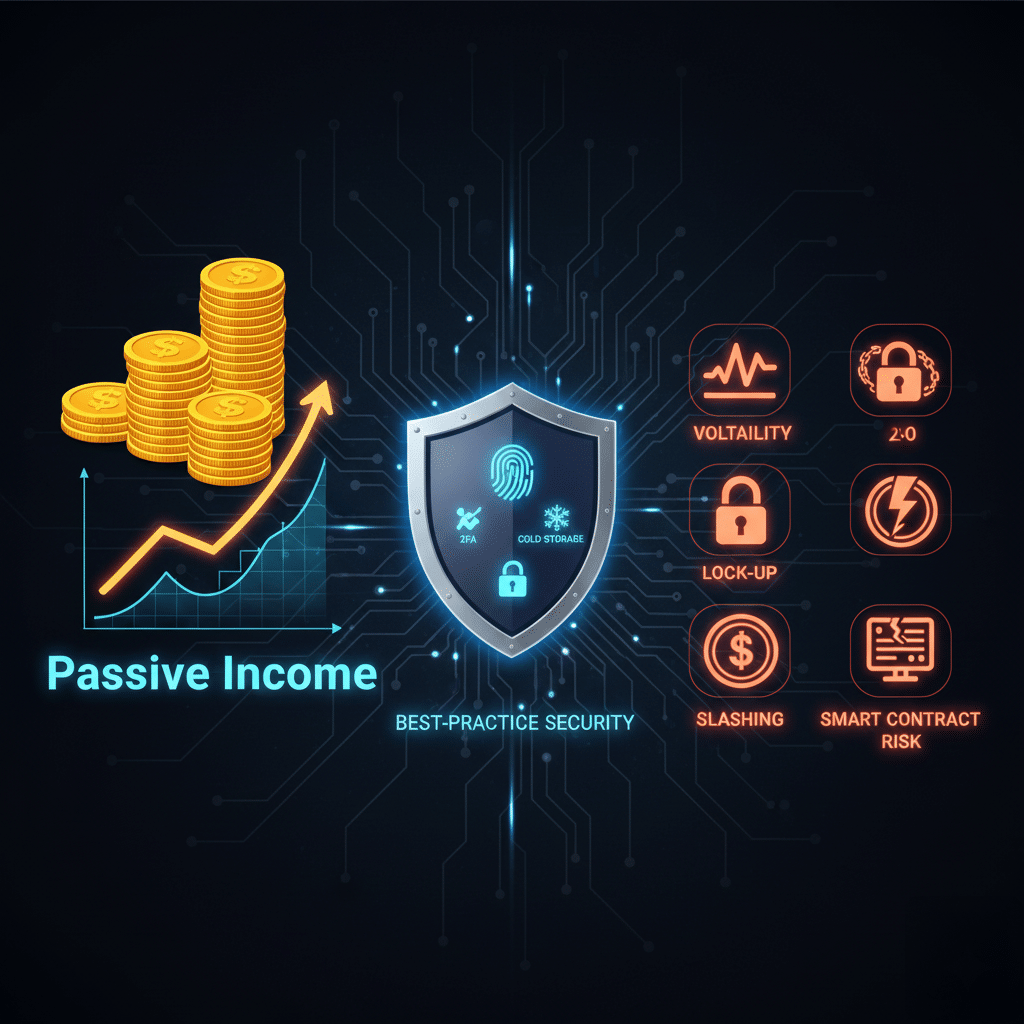
Illustration, not a performance chart or a security certification. The upward arrow is not a forecast; prices and principal can fall, and account controls do not eliminate investment or contract risk.
Is crypto staking permitted in the UAE?
The useful question is not whether a large international app works on your phone. It is which entity supplies the specific service, under which jurisdiction and permission, and whether you are eligible for it. An exchange authorisation is not automatic approval for every staking, custody, lending or yield product.
Dubai: VARA has an explicit custody-staking rule
VARA’s custody-staking rules say a custody VASP may provide Staking from Custody Services only when VARA explicitly authorises it and that authorisation is expressly included in the licence. This is more specific than saying guidance is merely evolving. VARA’s jurisdiction covers Dubai, excluding DIFC; it is not a single blanket licence for every UAE jurisdiction.
Use the public register to match the legal entity and permitted activities, then read the service terms. Ask for clarification if a global brand offers a product that the local entity’s permission does not establish. The brand, account and contracting entity are not interchangeable.
ADGM: a finalised framework, not a general presumption
ADGM’s FSRA announced its finalised staking framework on 29 April 2026. It sets categories of Authorised Person and requirements for staking clients’ virtual assets. That is not evidence that every ADGM business or international exchange is permitted to offer every product to every retail customer. Check the firm’s actual financial-services permission and client terms.
Direct personal protocol participation, operating validators commercially and selling a service to customers need different assessments. This guide is not a determination that a proposed business or personal arrangement is lawful. Get advice on the actual activity rather than treating a discussion of one regulator as a UAE-wide legal opinion.
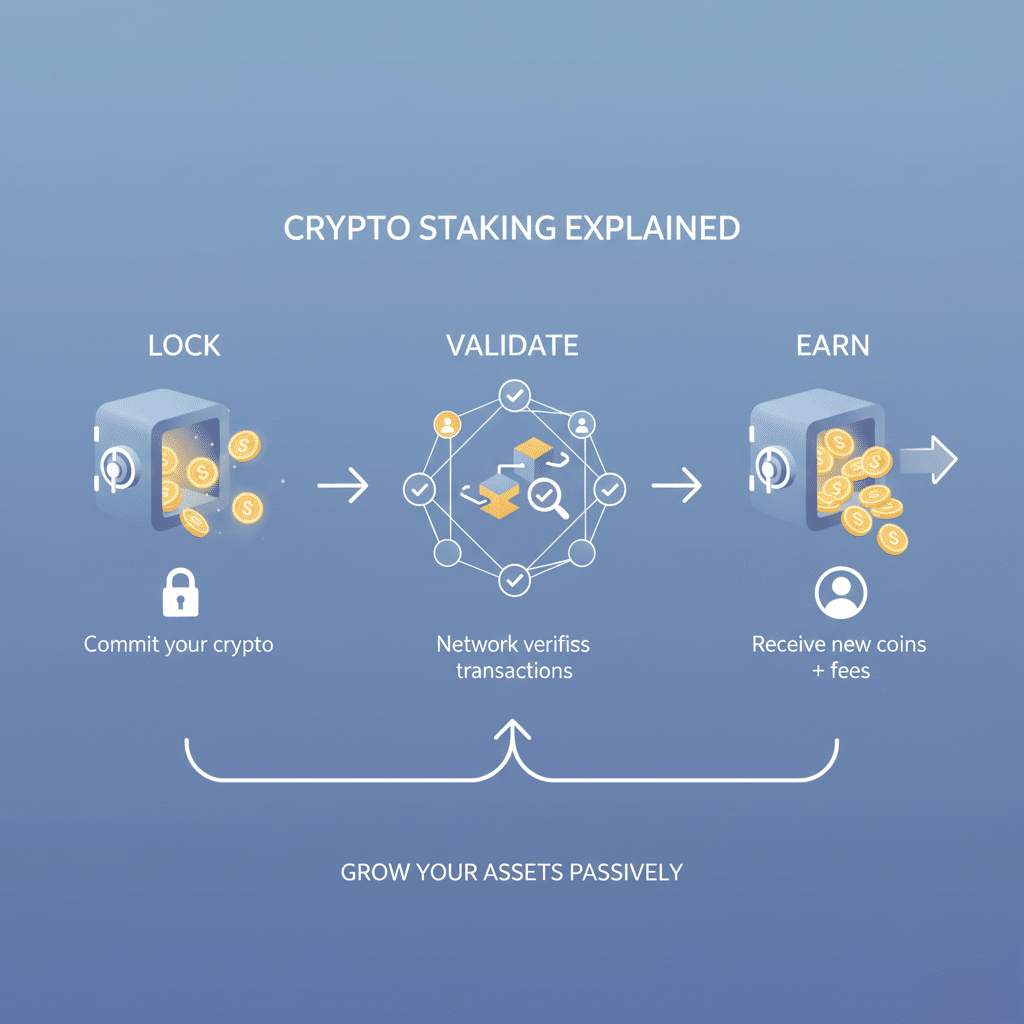
This simplified “lock, validate, earn” illustration is not universal. Some native delegation leaves assets spendable, while other arrangements have activation and exit queues. Rewards and fees depend on the network and service.
The documents I would ask for before accepting custodial staking
For a VARA-authorised custody-staking service, I would ask for two things separately: the client agreement and the risk disclosure. VARA’s risk-disclosure rule requires the latter to be separate from the agreement, with the client’s acceptance obtained independently before the service starts. A generic risk sentence beside an APY is not a substitute for understanding those documents.
| What I want to establish | What I would ask the provider | My decision if it remains unclear |
|---|---|---|
| The source of rewards | Which network activity or other source generates the payment, and which fees reduce it? | I would not compare the advertised rate as if it were a net return. |
| My exit rights | Who can request withdrawal, what can prevent it, and what happens if either party terminates? | I would not commit money needed on a fixed date. |
| Losses and recourse | Which losses can reach my balance, what can change in the terms, and where do I lodge a complaint? | I would not treat a licence or a support chat as a reimbursement promise. |
Those questions map to the regulator’s client-agreement requirements, which cover reward sources, calculations, charges, control and withdrawal conditions, termination and complaints. They are specific to this regulated service, not a universal description of every self-custody protocol.
My practical request would be: “Please identify the legal entity, the staking permission and the dated terms for this product. Point me to the reward calculation, every charge, the conditions that can delay withdrawal and the complaint route.” I would save the documents and the reply together. That is far more useful than a screenshot of the headline yield.
Four networks: the exit rules are not interchangeable
Ethereum: withdrawals already exist
Ethereum’s documentation gives a 32 ETH minimum for a solo validator. Smaller participation through pools adds different dependencies. There is no new native “ETH2” token that an owner must buy to migrate ordinary ETH.
The earlier claim that ETH is locked until a future upgrade enables withdrawals is outdated. Staking withdrawals are live. Exiting still involves the applicable network queue, and a pool or exchange can add its own redemption process. Being able to request an exit is not the same as instant access to spendable funds.
Liquid staking can provide a token representing a position, but selling that token and redeeming the underlying ETH are different routes. Its market price can diverge from the underlying claim, while contracts, governance and operators add risks. I would not call a receipt token “cash-like” merely because it is tradable.
Solana: check the validator and timing
Solana’s staking guidance ties rewards to inflation, total network stake, validator uptime and commission. Those variables make a fixed, undated APY range a poor substitute for the current offer. Check the wallet’s actual activation/deactivation status and the applicable network rules rather than assuming another network’s lock-up applies.
Cardano: native delegation does not lock the spending balance
Cardano’s native delegation guide says ada remains in the wallet and spendable. Delegation to a pool does not mean sending your ada to a stranger’s personal address. Pool performance, fees and reward timing still matter.
Cardano’s current governance FAQ distinguishes pool delegation from the active vote delegation needed to withdraw rewards: a DRep, Abstain or No Confidence are the published options. It describes removing that requirement as a proposed future change, not a change already live. That distinction—spendable principal versus withdrawing rewards—is more useful than describing everything as flexible and stopping there. An exchange product using ADA can have its own terms.
Polkadot: distinguish the participant and the current rules
Do not copy an old 28-day withdrawal figure into every new staking comparison. The developer documentation discusses changes towards approximately two-day nominator unbonding. A 6 July 2026 community update on the official forum reports enactment of Referendum 1910, removing nominator slashing and shortening new nominator unbonding requests, while distinguishing validators and existing requests.
The documentation and dated community report are not a live examination of your account. Check your role, the current runtime and the actual request shown in the staking interface. A custodial provider can also impose additional processing. I would not use a validator’s rules to promise a nominator’s withdrawal date—or the reverse.
Illustrative regulator graphic, not an official register entry, authentic regulator branding or proof that a platform is licensed. Follow the actual regulator links above for permission checks.
APY is not your return in dirhams
APR is an annualised rate without the same compounding assumption as APY. Read how the provider calculates its number: gross or net of commission, estimated or promotional, historical or forward-looking, and for which balance tier. A promotional rate paid in another token is a different exposure from rewards in the asset you committed.
Reinvesting rewards can compound them, but only under the actual terms and costs. It is different from restaking, which can commit an existing staking position to additional protocols and risks. “Boosted” yield is a reason to ask where the extra return comes from, not proof of a better deal.
A worked loss example
This is an illustrative calculation, not a forecast, offer or recommendation. Assume 1,000 tokens cost AED 1 each, a year produces 80 reward tokens, and the provider takes 10% of those rewards—not 10% of the principal. Assume the asset then sells for AED 0.70.
| Calculation | Result |
|---|---|
| Starting purchase | 1,000 × AED 1 = AED 1,000 |
| Gross rewards | 80 tokens |
| Reward commission | 80 × 10% = 8 tokens |
| Closing token balance | 1,000 + 80 − 8 = 1,072 tokens |
| Closing value | 1,072 × AED 0.70 = AED 750.40 |
| Change before other fees and any tax | Loss of AED 249.60, or 24.96% |
The token balance increased while the dirham value fell. Deposit, conversion, network and withdrawal costs could make the outcome worse. This is why I would ask for a downside calculation before an explanation of maximum yield. It makes the risk visible instead of leaving it in a disclaimer.
How to assess a platform without a “best exchange” shortcut
Binance, Coinbase and Kraken appeared in the previous version as suggested options. Their global names are not enough to substantiate a UAE staking recommendation. This review does not establish that all three currently offer the same service, AED funding route or retail eligibility here, and does not rank them as the safest choices.
Use a product record instead of transferring a brand’s general reputation to every offer:
- Entity and permission: legal name, regulator, permitted activity, client classification and the service being purchased.
- Mechanism: native staking, pool, liquid token, lending or another source of yield.
- Control: who controls withdrawal keys, where assets go and what claim you hold.
- Costs: commission, conversion spread, entry/exit fees and who bears penalties.
- Exit: network queue, provider processing, redemption versus sale, and any freeze rights.
- Evidence: dated terms, actual disclosures and relevant audit scope—not a claim that proof of reserves or an insurance fund guarantees your balance.
Regulatory permission does not guarantee an investment return. An audit does not guarantee the absence of vulnerabilities. Diversifying providers can change concentration, but several products can still depend on the same underlying asset, contract or operator. More accounts do not automatically mean independent risk.
Funding and the first transaction: decide before depositing
- Establish eligibility first: confirm the exact service and local entity before submitting funds or identity documents.
- Compare the funding route: bank, card or crypto transfers have different fees, settlement and account-name requirements. Do not assume AED transfers are available because a platform accepts UAE users.
- Check asset and network: the supported deposit network, destination and any required memo or tag must agree. A small test can reduce an address mistake’s size; it does not prove a service is safe.
- Read the staking instruction: amount, validator or pool, rewards, fees and exit conditions. An Earn tab is not a complete explanation.
- Retain a transaction record: timestamp, asset units, fees, transaction hash or order reference, provider terms and applicable AED valuation record.
I would stop before depositing if the provider cannot answer the mechanism or exit questions. Completing KYC is not proof of authorisation or solvency. Do not bypass restrictions or move a conversation to an unofficial payment channel to make a blocked product work.
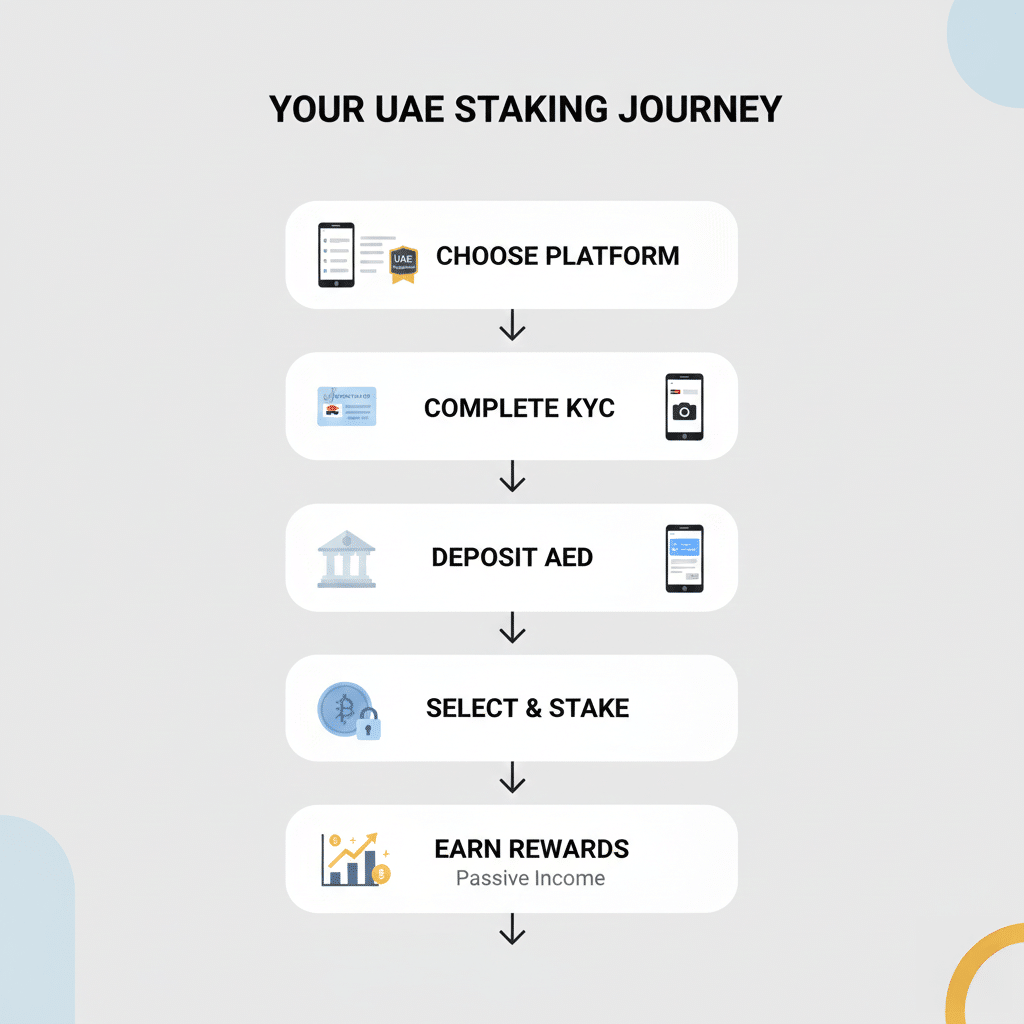
Conceptual journey, not an actual app screen or a confirmed provider workflow. AED funding, staking eligibility and rewards must each be established separately; the diagram does not promise income.
Loss controls: what each measure actually covers
Ethereum’s security guidance stresses keeping recovery phrases private, checking destinations and reading what a transaction authorises. A hardware wallet protects private keys; it does not reverse a malicious approval or guarantee a contract’s safety. Depending on the network, delegation can be authorised while retaining wallet control—there is no universal need to move everything to an exchange to stake.
For custodial accounts, use the provider’s supported strong authentication and official recovery process. Do not give a supposed support agent a seed phrase, private key or remote access. Check domains independently rather than trust a search advertisement or a direct message promising to unlock rewards.
Ethereum distinguishes penalties, slashing and an inactivity leak. Ordinary missed duties and slashable conflicting behaviour are not the same event. Other networks implement different rules, so “any validator going offline slashes your principal” is not a reliable universal explanation. Establish how losses are passed to you under the specific arrangement.
UAE tax: classify the activity, not the marketing label
The FTA’s natural-person guidance applies Corporate Tax where a person conducts UAE business or business activities and the associated calendar-year turnover exceeds AED 1 million. Qualifying personal investment income is excluded from that business test. The threshold is not the amount staked, the token portfolio’s value or a taxable-profit allowance.
The FTA’s detailed natural-person guide defines the personal-investment category; it is not a blanket exemption for anything called crypto. Running validators for customers, providing services or operating commercially needs its own assessment. Foreign tax obligations can also remain relevant.
Keep reward, fee, purchase and disposal records and a consistent valuation trail. An internal transfer between your own wallets is not the same record as a reward, service receipt or sale. Our UAE crypto-tax guide develops those distinctions. Ask a qualified adviser to assess the actual arrangement; this article does not determine anyone’s tax liability.
My verdict: understand the obligation before chasing the reward
A clear exit and a clear source of rewards matter more than a large percentage. Staking can serve a network and earn tokens, but it does not convert a volatile holding into dependable spending money. I would reject a product that hides its mechanism behind “passive income,” even when the app looks polished.
Read the permission, record the terms and calculate a falling-price case. If you cannot explain who controls the assets, how losses arise and when funds can be withdrawn, the research is not finished. Choosing not to commit is a valid outcome—not a missed opportunity that a guide should pressure you to correct.
For related explanations, see our UAE cryptocurrency coverage, Ethereum sentiment and staking guide and practical crypto introduction.
Review scope: public protocol documentation, relevant VARA custody-staking rules, the ADGM framework announcement, FTA natural-person guidance and the supplied imagery, reviewed on 19 October 2026. On 21 October, the custody-staking client-document requirements and Cardano withdrawal distinction were rechecked, with additional protocol and FTA source checks; no current provider offer or user account was tested. This is general education, not personalised investment, legal or tax advice, a complete review of every applicable rule, a platform security audit or a test transaction. Capital can be lost.