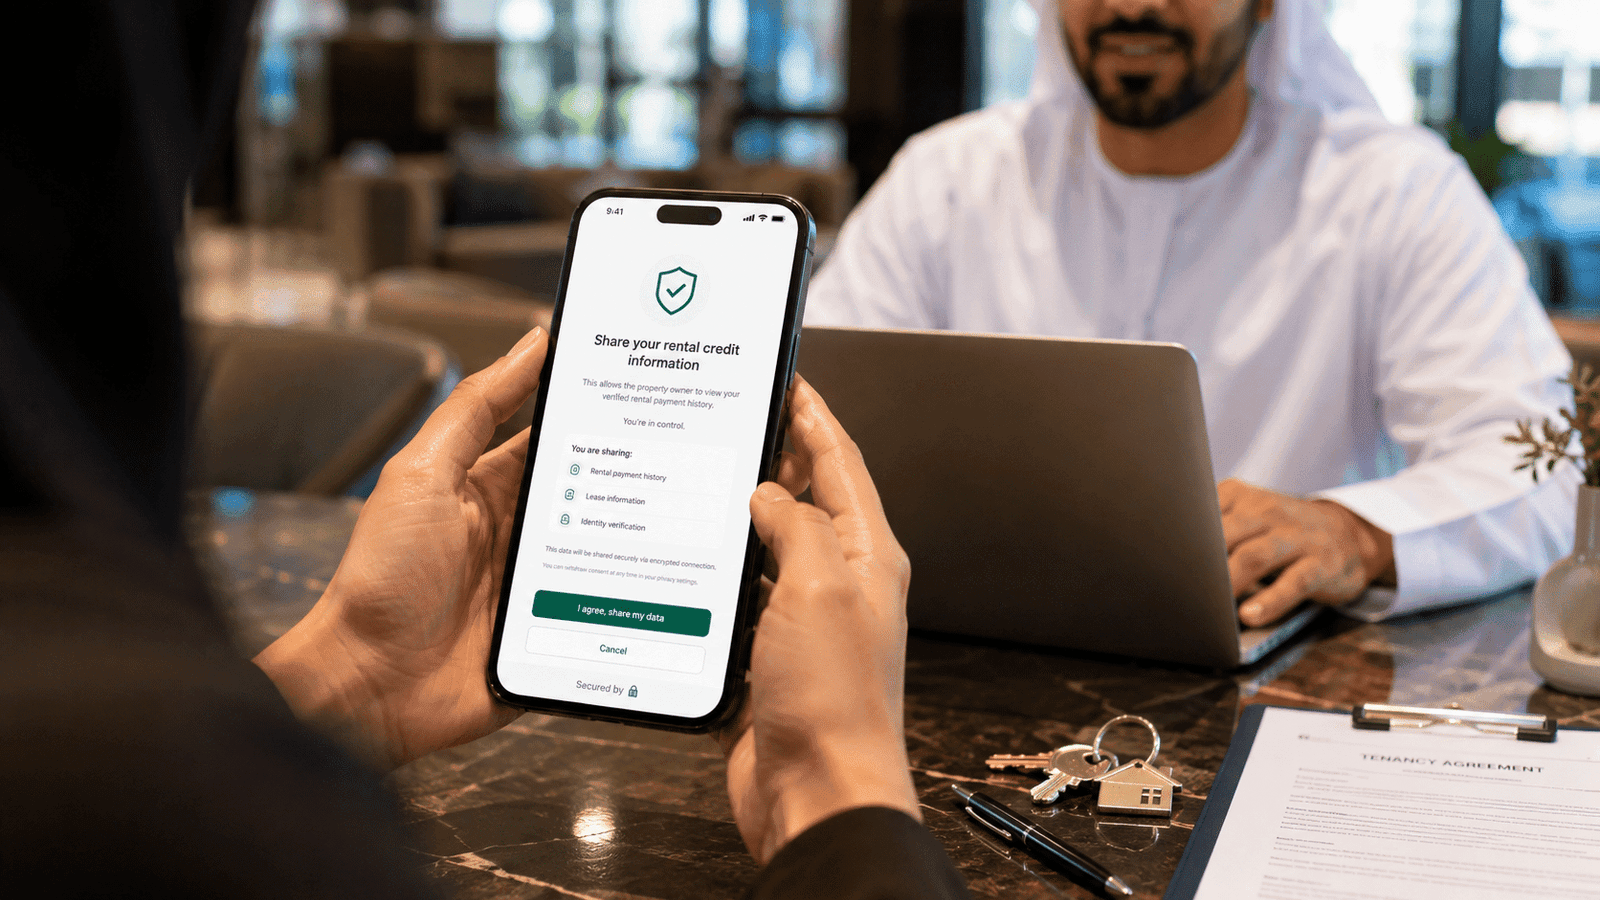
How UAE tenant screening works: AED 10.50 requests, UAE PASS consent, score versus full report, new Credit Score 3i ranges and checks before approving.
A landlord can request your UAE credit score through Etihad Credit Bureau’s Tenant Screening service, but the score is released only after you approve through UAE PASS. The published request fee is AED 10.50. This is a screening tool, not a new visa requirement or a guarantee that a landlord will accept you. The useful questions are who is asking, what they will receive, and whether your credit file is being read in the right context.
There is an important distinction from the older description of this service: the landlord receives the Tenant Score, not your detailed credit report. The bureau also now describes different Credit Score 3i ranges for established and new-to-credit files. A blanket “300–900” scale is not the current explanation to use.

What happens when a landlord requests your score?
The bureau’s service page says a landlord enters the prospective tenant’s Emirates ID, pays per request and sends a consent request through UAE PASS. The score becomes available after approval; if the tenant declines, the requester receives a full refund. The service is available to landlords, property managers and authorised brokers. A message claiming to come from one of them is not enough: check the requester in the real app.
- Confirm that the request relates to a property application you actually made.
- Read the name and scope before approving. If the identity is unclear, verify it independently with the agent or landlord.
- Do not send a UAE PASS PIN, approve an unrelated sign-in or forward one-time passwords to someone asking to “help”.
- Keep the property and agent correspondence so the purpose of the request is clear.
The official FAQ says sharing is optional and that a high score does not guarantee rental approval. A landlord can consider other information. Approval to share a score should therefore not be mistaken for approval of the tenancy, rent or cheque arrangement.

A score is not the same as the full report
| Product or document | What it is for | What not to assume |
|---|---|---|
| Tenant Screening | A consent-based score for rental assessment | That the landlord automatically receives every account, balance and payment entry |
| Your personal Credit Score | A snapshot of your credit standing | That the number alone explains every factor behind it |
| Your personal Credit Report | More detail about your credit history and the factors behind it | That buying it is mandatory for every tenancy |
| Salary or employment evidence | Current circumstances relevant to the application | That it is replaced by the score or proves every future rent payment |
The bureau’s score/report comparison lists a personal score at AED 10.50 and a personal report at AED 84. Those are distinct products, not additional fees automatically charged to a tenant when the landlord requests screening. If someone asks you to buy and forward a whole report, understand that this is a broader disclosure than approving the score-sharing service.
Credit Score 3i: do not compare unlike files
Etihad Credit Bureau’s current Credit Score page describes a Mature Score range of 300–850 for established customers and a New-to-Credit/New-to-Country range of 300–650 for limited-history customers. The segment depends on the file’s depth. Limited history is not the same statement as a documented record of missed rent.
| Illustrative situation | Question to ask | Incorrect shortcut |
|---|---|---|
| A new arrival shows a score of 600 | Which segment and band does the bureau actually show? | Judging it against an assumed old 900-point scale |
| Two applicants both show 600 | Are the files the same segment and how recent are the results? | Treating the identical number as a complete comparison |
| No Tenant Score appears | Does the bureau have enough relevant information? | Calling the absence proof of unreliability |
These examples explain interpretation; they do not assign an approval threshold, label a particular person creditworthy or turn a score into a probability of paying rent. Use the bureau’s own segment and explanation. A screen showing “approved” in an illustration is not a real tenancy decision.
What a new resident can prepare without taking on debt
Ask what the landlord needs in addition to screening. A current employment letter, documented income or references may help explain circumstances the score does not describe. Provide only relevant documents through an agreed channel, and consider redacting unrelated sensitive information where accepted. Do not fabricate a rental history or borrow money simply to create one.
More cheques are not more money paid upfront: they divide the same rent into different due dates. A larger deposit is a separate commitment. If either is proposed, compare the actual schedule and written terms rather than assuming it automatically improves an application. Never hand over extra money solely because someone claims it will “fix” your credit score.
Pay existing obligations on time and check inaccuracies through the bureau’s correction route. Opening a new card solely to look creditworthy introduces a separate credit decision and potential costs. This guide does not recommend new borrowing to qualify for a tenancy or promise a fast score increase.
If the file is wrong: correction before another screening
A low number and an inaccurate entry are different problems. The bureau’s official Data Correction page, read on 9 November 2026, offers a free correction service for a Credit Report purchased within the last 30 days. That is a condition of this service, not a requirement that every rental applicant buy a report.
- Identify the particular incorrect or missing entry and the information provider. The bureau’s FAQ says a missing facility can be identified by the bank name and facility type.
- Use the bureau’s own correction route. Its instructions request an Emirates ID copy and relevant supporting documents; submit those only through the official channel, not to a stranger offering a score repair. Submit separate correction requests when different information providers are involved.
- Keep the confirmation and follow the response. The bureau contacts the information provider; it says it does not itself add or edit the provider’s data. Its service steps describe an expected update within 10 working days, not an instant score increase or rental approval.
The page’s FAQ says to reply to the request email if 10 days pass without an update. If the provider rejects the correction, it directs customers to 800-BUREAU (800-287328) to register a data-correction dispute, with the relevant information ready. That dispute route follows a rejected correction request; it is not the first step for simply disliking a score. Neither a correction request nor a bureau response reserves a property or extends a tenancy deadline.
For the rental conversation, ask the agent to confirm the application deadline and whether they will consider the other documents already supplied while a specific entry is being checked. Do not promise that a pending correction will change the number, and do not send a complete credit file merely to prove that a request exists. No private file or correction submission was tested for this guide.
A request budget for landlords
The cost of several consented score requests
Illustrative request volume; dated price
At the article’s AED10.50 published unit price, ten requests total AED105 before any applicable refunds.
Methodology
Uses the guide’s dated price for a personal score, not a full credit report. Illustrates gross request costs, not an automatic fee charged to a tenant.
Read chart data
| Comparison | Cost at AED10.50 each |
|---|---|
| 1 requests | 10.50 |
| 3 requests | 31.50 |
| 5 requests | 52.50 |
| 10 requests | 105.00 |
At the published AED 10.50 fee, five separate requests would total AED 52.50 before any applicable refunds: 5 × 10.50. This is our arithmetic, not a subscription price. The service page describes a refund on decline, so do not count every initiated request as a permanently paid completed screening. Confirm the current payment and refund terms in the service.
Use a consistent, relevant assessment rather than a number detached from context. Confirm the applicant and property, request only what is needed, and handle personal information carefully. A bureau score is one input—not a character reference, proof of future payment or a substitute for the agreed lease and lawful procedures.
A rental check is not Ejari approval
Do not conflate a landlord’s screening request with tenancy registration. For Dubai tenancy-registration requirements, use DLD’s applicable service instructions. This review found no basis to describe this bureau service as a universal new legal prerequisite for every UAE rental. Rules and procedures differ by emirate; an individual landlord’s application process is not a nationwide tenancy law.
For a renewal increase rather than a new application, see our Dubai rental-index guide. A credit score does not calculate the permitted renewal increase or decide a dispute.
Sources and scope
Reviewed on 18 October 2026 against the bureau’s public Tenant Screening, Credit Score and Personal FAQ content, including the public page data used by its website. We have not run a screening, viewed a private credit file or verified a particular agency’s adoption. The original article images remain illustrations; they are not screenshots proving an actual tenant approval. For an error in your file, use the bureau’s official support and correction process rather than a seller promising to erase a record.
Questions answered
Must I approve a Tenant Score request?
The bureau says score sharing is optional and requires your explicit consent through UAE PASS. A high score does not guarantee that a landlord will accept the application.
Does Tenant Screening share my detailed credit report?
No. The bureau’s FAQ says the landlord receives only the Tenant Score, not the detailed report.
Is every credit score measured on a 300–900 scale?
No. The bureau currently describes Credit Score 3i segments of 300–850 for mature files and 300–650 for new-to-credit or new-to-country files.